Why Deals Fall Through After Everyone Said Yes
Everybody said yes. The offer was made, accepted and signed. The lender has the file, the title company opened it, the inspection is scheduled, and you changed the status to pending.
Then it died.
If you have been doing this a while you have lived it more than once, and you have probably filed it under bad luck. In this market that filing is costing you money, because a meaningful share of these are not random.
One In Seven — And Almost None Of It Is A National Number
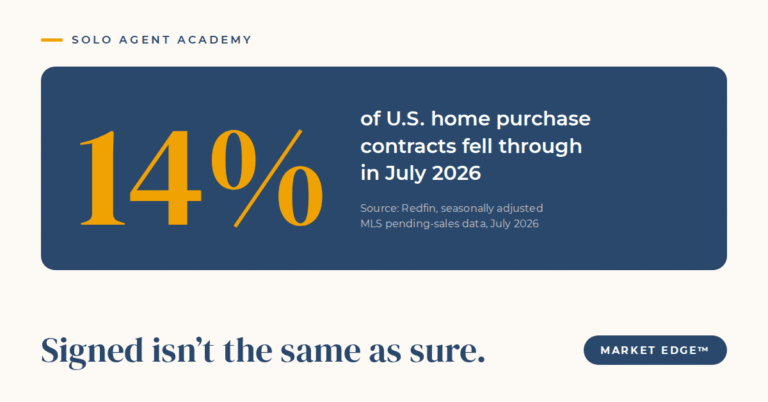
Nationwide, 14% of home-sale agreements that went under contract in July 2026 fell through, the highest share in nearly three years on a seasonally adjusted basis, up from 13.7% a month earlier. Roughly one in seven.
The national figure is also the least useful one in the report. The spread between metros is where the actual information is.
Cancellation is not a national condition. It is a local one, and the range is nearly six to one.
Highest cancellation rates
Share of July 2026 agreements that fell through
Lowest cancellation rates
Share of July 2026 agreements that fell through
Where buyers have little to choose from, they hold deals together. Where they have plenty to choose from, they leave. Your own number depends far more on which of those two markets you work in than on how the national average moved.
Sources: Redfin, “With Buyers Firmly in the Driver’s Seat, Home-Purchase Cancellations Hit Highest Level in Nearly 3 Years,” August 21, 2026, based on a Redfin analysis of seasonally adjusted MLS pending-sales data. Population: home-sale agreements that went under contract in July 2026 among the 50 most populous U.S. metropolitan areas with sufficient data. Geography: United States.
Two other figures from the same market give the national number its context. Redfin reported a near-record 51% more sellers than buyers in the market in July, and a median U.S. sale price of $407,730 against an average 30-year mortgage rate of 6.54% — the highest July price on record at a one-year rate high.
Those are not separate stories. A buyer with seventeen alternatives and a record-high payment is a buyer with both the option and the motive to reconsider.
What This Number Does Not Say
Before anybody builds a listing presentation on 14%, three things need stating plainly, because the figure is about to be misused across the industry.
It is not a spike. The share of U.S. deals falling through has moved between roughly 13% and 14% for four years. July 2026 was the top of a narrow band, not a break from it.
It does not mean agents cause 14% of failures. Nobody measured that. Jobs are lost, financing fails, inspections find real problems, appraisals expose real valuation issues, insurance becomes unavailable, title defects surface, lives change.
And it certainly does not mean compensation confusion causes 14% of failures. That number has never been measured either, and if you see it claimed anywhere, somebody built it out of two unrelated figures.
What the number does support is narrower and more useful: in a market where roughly one in seven agreements does not close, the failures you can control deserve more attention than they have been getting.
The Contract Is A Finish Line Only For You
Something happens to an agent when a contract gets signed. The status changes, the graphic goes up, the CRM updates, you congratulate your seller and tell your buyer they got the house. Emotionally, the file moves into closed.
Your client experiences none of that. They committed based on what they knew in the moment they signed, and then the transaction starts handing them new information almost immediately.
The inspection finds a roof. The insurance quote lands high. The appraisal comes in low. The lender revises the cash needed. A repair estimate arrives. The seller refuses a concession. Your buyer does the math on what will be left in their account the week after closing.
Now they are not deciding whether they want the house. They are deciding whether they want this house, at this price, plus a $20,000 roof. That is a genuinely different question, and they are answering it for the first time.
Your seller gets the same treatment from the other side. Repair requests, a low appraisal, a buyer asking for another $10,000, a moved closing date, and an updated net figure that looks nothing like the one in their head when they accepted.
A Cancellation Is A Decision, Not A Personality
The industry has a shorthand for all of this and it is worth retiring. Cold feet is not a diagnosis. It tells you a client hesitated and nothing about why, which means it cannot be acted on.
“The buyer got cold feet” is the sentence agents use when nobody asked what changed.
Something specific created that hesitation. The monthly payment. Cash left after closing. Fear of more hidden problems. A misunderstanding about closing costs. An unexpected obligation to their own brokerage. A job concern. Family pressure. Another property. A seller who has said no four times.
Each of those has a different response, and you cannot choose one until you know which you are looking at.
Commitment Is A Stage, Not A Signature
This is the part of the Decision Gap Loop™ that agents skip. The loop runs awareness, desire, hesitation, rationalization, commitment — and then re-engagement, because consumers move backward.
Commitment is not permanent. It is a state based on the information a person currently holds. Change that information materially and you reopen the decision, whatever the contract says.
Which means a failing transaction is diagnosable. When the inspection comes back badly, your buyer has usually dropped from commitment to hesitation, and the work is to identify precisely what changed, help them rationalize the new facts — get estimates, understand the repair, negotiate where appropriate, determine whether the economics still work — and then let them arrive at commitment again, or at an informed no.
When concessions stack up on a seller, the same thing has happened to them. Agents make it worse by negotiating items one at a time. “It’s only $2,500,” then “just another $3,000,” then “they want a $5,000 credit.” Individually manageable. Collectively $10,500, and your seller is now in hesitation about a decision they made three weeks ago.
Update the net sheet and ask one question: does this transaction still accomplish what you needed it to accomplish? That is not deal-saving. That is representation, and it is also the only version of this conversation that survives a complaint.
The Truck
Early in my career in Tucson, a buyer bought a new truck seven days before closing. The payment moved his debt-to-income ratio, the lender pulled the approval, and the transaction ended. My broker would not help me soften the news, the seller’s response was that he should just sell the truck, the buyer refused, and the earnest money went back. The full story is in The Deal That Died Over a Truck.
It was one of my first closings and I could not have stopped him from buying a truck. But I have thought about that file for twenty-five years, and here is what it taught me: he did not know that a truck payment could cost him the house. Nobody had told him, because nobody had thought to.
Some transactions die of things you could never have reached. Others die of things nobody said out loud in time.
Build Checkpoints Instead Of Waiting For The Call
Do not wait for a client to tell you they are panicking. By then they have been deciding alone for days.
Put a checkpoint at each place the transaction hands your client new information. When the offer is written: does the buyer understand the estimated financial commitment? When it is accepted: has anything changed from what they expected? After the inspection: what specifically changed about the decision? After the appraisal: do the price and the cash requirement still make sense? After any negotiation: update the buyer’s costs and the seller’s net. When financing changes: does the buyer understand the new payment or cash figure? Before contingencies expire: is your client still deciding with current information? Before closing: do the final figures resemble what they have been expecting?
That is eight conversations, most of them two minutes long. None of it requires new software, and it is the part of your file that a transaction coordinator cannot do for you.
One discipline makes all of it work: when a client says they are not sure anymore, ask why before you start fixing. Agents are trained to be deal savers, so the reflex is to call the lender, call the other agent, ask for a concession, find a roofer, cut your own fee. You can spend two days solving a roof problem for a buyer who is actually frightened about their monthly payment — or reduce your commission when your compensation had nothing whatsoever to do with it.
Diagnose the decision before you prescribe a solution.
Your Job Was Never To Close Every Contract
Sometimes the right answer is to proceed. Sometimes it is renegotiate, or get more information, or wait, or terminate if the agreement and the circumstances give your client that right. A closing is not proof you represented someone well, and a termination is not proof you failed.
The standard is whether your client had the information they needed to make the decision.
Which is where this three-part series lands. Your fee does not need to hide; it needs to make sense. Before anyone signs, a buyer should know what they could owe and a seller should know what they could net. And a signature does not end the decision — it starts the part where you keep your client informed enough to stay confident in it.
One in seven agreements did not close last July. You cannot get that to zero. But it is worth asking, honestly, how many of yours were truly unreachable — and how many contained a decision gap that nobody named in time.
Sources: Redfin, “With Buyers Firmly in the Driver’s Seat, Home-Purchase Cancellations Hit Highest Level in Nearly 3 Years,” August 21, 2026 (U.S. cancellation share, metro detail, and the 51% more sellers than buyers figure). Redfin, “Home Sales Drop to Lowest Level in Nearly 2 Years,” August 2026 (median U.S. sale price of $407,730 and average 30-year mortgage rate of 6.54%, July 2026, United States). Both are Redfin analyses of MLS and market data; figures are reported side by side and are not combined into any derived measure.
One next step
Find out what actually changed before you try to fix it
The Buyer Hesitation Diagnostic walks you through identifying which specific concern moved your client backward, so you solve the real problem instead of the loudest one.
Open the Buyer Hesitation Diagnostic →